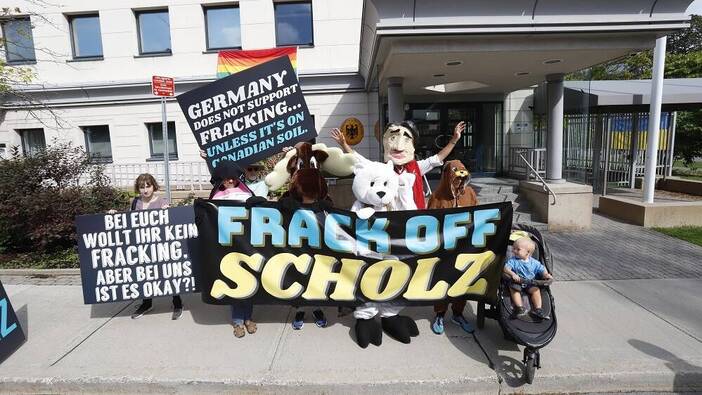Since the start of the war in Ukraine, Germany and the EU have sought to free themselves from their dependence on Russian gas imports, primarily by importing liquefied natural gas (LNG). The price of LNG on the world market was already rising in late 2021, and the additional demand from Europe significantly exacerbated its continued climb. On average, the price of short-term LNG purchases in 2022 was twice what it was in 2021, reaching an all-time high in the summer of 2022.
For poor countries that relied on LNG imports for their energy needs, the effects were disastrous: they could no longer afford necessary gas imports, were no longer offered gas, and in some cases gas deliveries that had been promised were cancelled. Pakistan, which suffered the destructive power of a hundred-year flood last year, is one such example. It is a country dependent upon LNG imports, which dropped over the past year by almost 20 percent. As a result, there were blackouts, and the country’s manufacturing sector suffered. A similar fate befell Bangladesh, with its textile industry, which is a central part of the national economy, severely impacted by energy shortages. These countries have been forced to fall back on oil to produce electricity, which is worse for the environment, less efficient, and more expensive.
While LNG prices have declined since, increased demand from China due to the economic recovery it has experienced following the lifting of its COVID-19 restrictions — along with prolonged demand in Europe — could cause prices to rise again soon. Even if they do not return to the record levels seen in the summer of 2022, it will still be difficult for countries like Pakistan and Bangladesh to meet their need for LNG. In addition to rising energy prices, such countries also suffer from shrinking foreign currency reserves and poor exchange rates as well as economic crises that have intensified since the pandemic. The socio-economic consequences are devastating.
Egypt was also involved in Germany’s and Europe’s gas shopping spree over the past year. The country is in the midst of a serious economic crisis and in desperate need of foreign currency. As a result, the Egyptian government opted to export valuable gas while restricting its use in its own country and, among other things, burning extremely dirty mazut (a residue that results from the distillation of crude oil) to generate electricity. Of concern is that similar developments may occur in many countries, and fuels like oil and coal, which are extremely harmful to the climate, may be used more intensively again.
What is particularly interesting about the Egyptian example is that it is primarily Israeli gas that is supposed to be shipped via Egyptian terminals as part of the deal with the EU. Israel is now considering developing new gas fields along its coast, abandoning its prior environmental policies in the process.
Israel is not unique in this respect: the negative effects of the current energy policy are also becoming clear in Canada, another place where Europe would like to buy LNG in the future. Investing in fossil gas has been and remains a lucrative business in the country. Even if Canada seeks to stop using coal by 2030, a profitable market in Europe means that oil and particularly gas seem to have a bright future— in spite of all climate-policy imperatives. At the same time, in an updated version of old colonial models, it is seemingly deemed acceptable that these projects are frequently being undertaken on indigenous land without sufficient consideration for the rights of the people who live there.
Ahead of every other country in terms of LNG exports is the United States, which became the world’s largest LNG exporter in 2022. Although President Biden’s administration is officially pursuing more ambitious climate protection goals than its predecessor, it has no problem securing the future of its gas and oil industry by massively increasing export options.
In late 2022, the US government approved the construction of what will be the largest oil export terminal in the country, along with another LNG export terminal. The United States currently has seven operational LNG export terminals, with three more under construction. Europe functions as a core market, with LNG exports from the US to the EU more than doubling over the past year. These projects are highly problematic, and not only in terms of their negative impact on the climate: many of them are also intensifying environmental racism, given that they are being undertaken on the Gulf Coast of Texas and Louisiana, which is primarily populated by low-income, African-American, and Latinx people, whose homes are already being contaminated by oil and gas facilities.
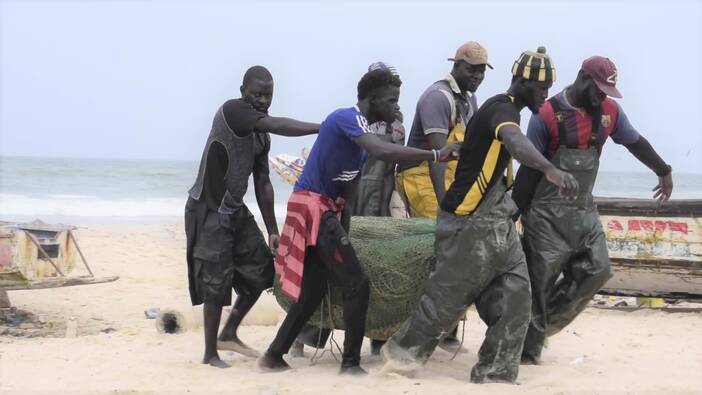
There is now also a long list of projects in Africa wherein Germany, the EU, or international corporations are planning to develop new gas and oil fields or expedite pipeline construction as part of cooperation and investment projects. Some of these projects have already provoked negative reactions in the press, such as the German government’s plans to participate in gas field development in a marine sanctuary off the Senegalese coast. A look at British corporation BP’s planned gas extraction operation off the coast of Saint-Louis in Senegal, set to begin this year, throws into sharp relief the dire consequences such a project is going to have on the local fishing community.
This is not only true of projects in Senegal: most of the planned energy projects in Africa will neither improve living standards for local populations nor secure their own energy supply. The valuable raw materials will go to Europe while the negative outcomes will affect local environments and economies. They could also trigger new conflicts, for instance over land use or control of new and lucrative business options.
The search for alternatives to Russian energy imports is also being accompanied by increasing demand for raw materials for Europe’s energy transition, the impact of which is falling on many African and Latin American countries. On top of all this is the hype around green hydrogen, which the EU also largely wants to import — through cooperative agreements that will only deepen the structural inequality between Africa and Europe, rather than redress it. Europe’s current energy policy is reinforcing the dependency of many countries in the Global South on exports of raw materials. It is a simple update of prior colonial models — only this time, the dictates of energy policy mean that they are being labelled as “green” alternatives.
The last year has shown that Germany and Europe are far from making energy policy decisions that are commensurate with the goal of keeping global warming below 1.5° C. The EU parliament has even declared natural gas sustainable. Panicked by empty gas reserves, the German government moved with lightning speed to establish a disproportionately large LNG infrastructure, buy overpriced gas, and thereby fuel the rise in gas prices on the world market. In doing so, it gave no consideration to poor countries.
A serious internationalist energy revolution could offer the countries of the Global South an opportunity to free themselves from dependence on exports of raw materials, which is urgently needed in light of the debt and climate crises. But current energy policy decisions mean that fossil fuels — in this case gas — will remain dominant.
The European gas industry will celebrate its enhanced position in late March with its European Gas Conference. It is a good thing that coalitions have come together and announced that they will protest against it or challenge European energy policy at their own alternative conference — and call attention to the effects of European gas policy on the Global South in the process.